Understanding the difference between cutting existing pensions and reducing future accrual
· Updated · No. 223
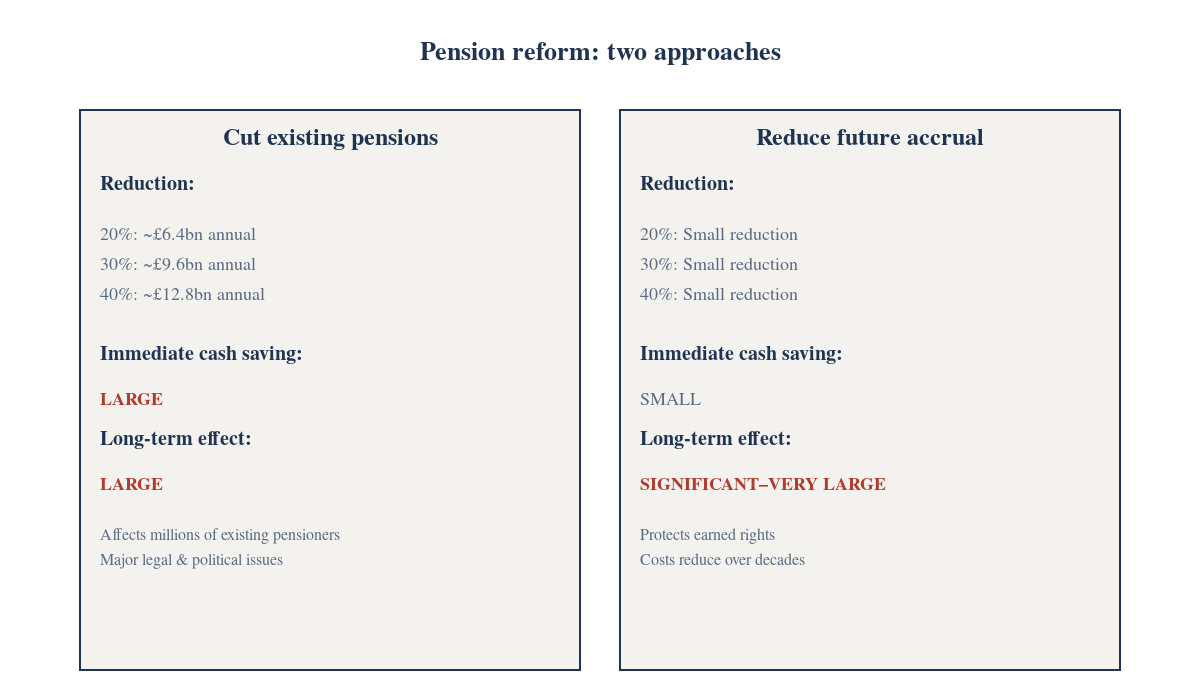
Cutting existing pensions would save cash immediately but affect current pensioners. Reducing future accrual saves little now but substantially lowers long-term liability as pensioners gradually transition to less generous schemes.
The important thing is to separate the £1.4009 trillion accounting liability from the annual cash saving. The government itself warns that the liability is a discounted estimate and is highly sensitive to assumptions; it is not a bill that could simply be reduced by 40% and immediately save £560bn.
The latest Whole of Government Accounts put unfunded public-sector pension liabilities at £1.4009tn at 31 March 2025.
1. If every existing pension were cut
This is the simple mathematical effect:
| Reduction | Liability before | Reduction in liability | Remaining liability |
|---|---|---|---|
| 20% | £1,400.9bn | £280.2bn | £1,120.7bn |
| 30% | £1,400.9bn | £420.3bn | £980.6bn |
| 40% | £1,400.9bn | £560.4bn | £840.5bn |
But these are only illustrative figures. They assume the whole liability is reduced proportionately. They should not be interpreted as the actual reduction in the government's future cash expenditure.
The reason is that the £1.4tn includes pensions already earned by current pensioners and accrued rights of current employees. It also incorporates assumptions about inflation, salaries, mortality and the discount rate.
2. What happens if you protect pensions already earned?
This is much more interesting.
Suppose the policy were:
Nobody loses pension rights they have already earned. From a specified date onwards, however, new DB pension accrual is reduced by 20%, 30% or 40%.
The immediate saving would be very small, because existing pensioners continue receiving their full pensions.
The large effect would accumulate over decades.
Imagine, purely for illustration, that:
Then:
| Future accrual reduction | Existing rights protected | Illustrative liability reduction |
|---|---|---|
| 20% | 70% | 6% |
| 30% | 70% | 9% |
| 40% | 70% | 12% |
Applied to £1.4009tn:
| Future accrual reduction | Illustrative reduction | Remaining liability |
|---|---|---|
| 20% | £84bn | £1.317tn |
| 30% | £126bn | £1.275tn |
| 40% | £168bn | £1.233tn |
But the 70/30 split is an assumption, not an official government figure - Not presented as a forecast.
3. Why future accrual is much more powerful than it first appears
There's a useful distinction here.
If someone has already worked 20 years under a DB scheme, cutting their future accrual doesn't erase those 20 years.
They might have:
20 years accrued -> protected
and then:
next 20 years -> lower pension accrual
.
That means the government gradually moves from the expensive old system towards a less expensive one without immediately reducing the income of existing pensioners.
Over time, the population receiving the old, more generous pension shrinks and the population receiving the lower accrual grows.
Eventually
If you reduced future accrual by 40%, after a sufficiently long transition the new generation of pensioners could have roughly 40% less DB pension earned through their employment, although the precise reduction in retirement income would depend on salary progression, years of service, inflation protection and the scheme's design.
That is quite different from taking 40% from somebody's pension tomorrow.
4. There is another important number
The government's accounts give the current service cost for public-sector pensions.
In 2024-25, current service costs net of employee contributions were £32.0bn.
That represents the approximate increase in the pension liability attributable to pension benefits being earned by employees during the year, after employee contributions.
If - purely as a simplified illustration - future accrual were reduced by 20%, 30% or 40%, you could initially think about the effect as:
| Future accrual reduction | £32bn current service cost | Approximate annual reduction |
|---|---|---|
| 20% | £32bn | £6.4bn |
| 30% | £32bn | £9.6bn |
| 40% | £32bn | £12.8bn |
But this is not an immediate Treasury cash saving.
The £32bn is an accounting measure of benefits being earned, not £32bn that the government would otherwise pay out this year.
This changes the argument considerably
Compare the two approaches:
Cutting pensions already being paid
40% cut
-> potentially around £24bn less gross annual pension expenditure based on the £60.4bn paid by unfunded schemes in 2024-25.
But it would immediately affect millions of existing pensioners and create major legal and political issues.
Changing future accrual
40% reduction
-> almost no immediate reduction in payments to existing pensioners.
But each year's new pension promises become smaller, potentially reducing the long-term liability substantially.
And the government's accounts explicitly identify current service costs as the increase in liabilities arising from current members' service during the year.
6. There's an even more important consideration
The Government's own figures show that the £1.4tn number isn't particularly stable.
For example, its 2024-25 analysis says:
a 0.5 percentage-point increase in the discount rate would reduce the unfunded liability by approximately £112bn.
Conversely, a 0.5-point reduction would increase it by approximately £112bn.
It also estimates that increasing assumed life expectancy by just one year would increase the liability by approximately £42bn.
So I would not describe £280bn, £420bn or £560bn as genuine government 'savings'.
They are the mathematical reductions in the reported liability if the entire accrued benefit were reduced by those percentages.
The policy comparison I'd use
If the objective is reducing the long-term burden on future taxpayers while protecting pensioners who have already earned their pensions, the interesting comparison is actually:
| Policy | Immediate cash saving | Long-term effect |
|---|---|---|
| 20% cut to existing pensions | Large | Large |
| 30% cut to existing pensions | Very large | Very large |
| 40% cut to existing pensions | Extremely large | Extremely large |
| 20% reduction in future accrual | Small | Significant |
| 30% reduction in future accrual | Small | Larger |
| 40% reduction in future accrual | Small | Potentially very large |
I think the next calculation should be more precise: rather than assuming 70%/30%, we can use the government's £32bn annual current-service cost, £60.4bn annual benefits paid and £1.4009tn liability to construct a 10-, 20- and 30-year transition model for 20%, 30% and 40% reductions in future accrual.
That would show approximately how much the annual government pension cost could fall in 2036, 2046 and 2056, rather than just changing the accounting liability on paper.

Comments
No answered comments yet. Yours could be the first.
Add a comment
Your email address is needed so we can reply, and is never shown on the site. Comments appear here once they have been answered.